
Planning
Personal Financial Planning Sparks Bright Futures
Personal financial planning reshapes money management using innovative budgeting and smart debt strategies, get ready for a twist that changes everything!
Ever wonder if a simple plan can brighten your financial future? Personal money planning isn’t just about keeping track of expenses, it’s like following a recipe that helps you balance spending and saving. When you take a close look at your income, bills, and goals, you create a strong foundation for stability and growth.
This isn’t just about crunching numbers. It’s about making smart choices today that build a better tomorrow.
How Personal Financial Planning Aligns with Your Money Management Goals
A personal financial plan is your roadmap to a stable, growing future. It lays out your income, bills, savings, debts, and investments, and sets clear goals to help guide your everyday spending. In short, it's a simple blueprint for managing your money smartly.
When you take a close look at what you own, owe, earn, and spend, you build a strong financial base. Think of it like collecting ingredients for a favorite recipe, each item counts, and everything needs to be measured just right. Here's a neat fact: many successful people kept track of every penny, proving that careful planning really does work.
Watching your cash flow lets you direct money exactly where it's needed, whether that's paying bills, tackling debt, or saving for that upcoming purchase. And don’t forget to set aside a little extra in your emergency fund, which acts like a financial safety net for those unexpected moments, such as a surprise bill or a short job gap.
By crafting a plan that tracks your money with clear, achievable targets, you're turning your financial goals into everyday actions that lead to stability and a brighter tomorrow.
Assessing Your Financial Situation in Personal Financial Planning
Start by making a simple list of everything you own and everything you owe. Write down your savings, home, and any other valuable things next to debts like loans or credit card balances. Subtract your debts from your assets to get your net worth. This clear snapshot of your money helps you see exactly where you stand and guides your next steps.
Then, track your monthly income and spending like you're keeping score in your favorite game. Jot down every paycheck and bill. When you see how much money comes in versus what goes out, you can spot ways to cut costs and boost your cash flow.
Also, think about finding extra ways to earn money so you're not depending on just one source. Maybe a side gig, freelance work, or a small investment could add a bit more to your earnings. It’s like adding another layer to your safety net.
Finally, when reviewing your investments, keep an eye on current market trends. Look at how the markets are moving, and adjust your choices if needed. And hey, using online tools (like mortgage, tax, or retirement calculators) can make figuring out your needs a whole lot easier. Give those financial planning tools a try and see how they can help shape your financial future.
Setting Clear Financial Goals in Your Personal Financial Plan
First, break your goals into three parts: short-term (about 1–2 years), medium-term (around 3–5 years), and long-term (over 5 years). For example, start with a short-term goal like putting aside $5,000 for an emergency fund in one year. This goal helps you feel secure by providing a safety net for surprises like a car repair or an unexpected doctor visit.
Next, set a medium-term goal. You might plan to save enough for a home down payment within three years. Having a clear target like this keeps you focused and encourages steady saving. Seeing progress over a familiar period can really boost your motivation.
Then, plan for a long-term goal. Think about building a $250,000 retirement nest egg over 20 years. A goal like this pushes you to invest smartly and stick to your plan, even when market ups and downs make things unpredictable.
Using a goal-setting approach like SMART (that means making goals Specific, Measurable, Achievable, Relevant, and Time-bound) can really help. For instance, you could set a target to cut your credit card balances by 50% in the next 12 months. Breaking down broad dreams into clear, simple steps lights the way to real financial growth.
Crafting Your Budget: A Step-by-Step Financial Planning Process
Start by keeping track of every little expense, whether it's that daily cup of coffee or your monthly streaming fee. Grab a simple spreadsheet or a budgeting app and jot down each cost. For instance, you might note, "I looked at my lunch bills and realized that skipping a few small snacks could lead to extra savings." Small changes can really add up.
Then, break your spending into two groups: must-haves and extras. Must-haves include things like your rent, bills, and groceries. Extras are things like movie nights or extra takeout meals. This simple step helps you see where your money is going and decide what you can trim.
Once you've organized your spending, divide your income into needs, savings, and wants. A well-known method is the 50/30/20 rule: 50% of what you earn goes to must-haves, 30% to extras, and 20% to savings or paying off debt. Start small by aiming for an emergency fund of $500, then bump it up to $1,000, and eventually cover one month’s living expenses.
Finally, check in on your budget regularly by comparing what you planned to spend with what you actually spent. Use easy tools like budget templates or mobile apps (simple programs that help you track spending) to keep up with progress. This method keeps your financial plan clear, simple, and in tune with your long-term goals.
Managing Debt in Your Personal Financial Planning Strategy
Cutting down your debt can ease your money worries and even boost your credit score (like how much of your available credit you're using). Paying off high-interest debts, such as credit cards or payday loans, is important because it frees up cash for other things you want or need.
There are two popular ways to tackle debt. One is the debt-snowball method, where you knock out the smallest debt first. This way, you get quick wins that can really lift your spirits, even if you might pay a little extra in the long run. The other way is the debt-avalanche method, which focuses on paying off debts with the highest interest rate first. This method can help you save money on interest over time.
It can also help a lot to ask your lenders for lower rates. Sometimes, you might even consolidate your debts into one simple monthly payment. This can make it easier to keep track and might lower the interest rate too. Setting aside a bit of extra cash for extra payments each month can speed up your progress. Even small extra amounts add up, chipping away at your balances and improving your credit score.
Stick with the approach that feels best for you, keep track of your progress, and don't forget to celebrate along the way.
Optimizing Savings and Investments in Personal Financial Planning
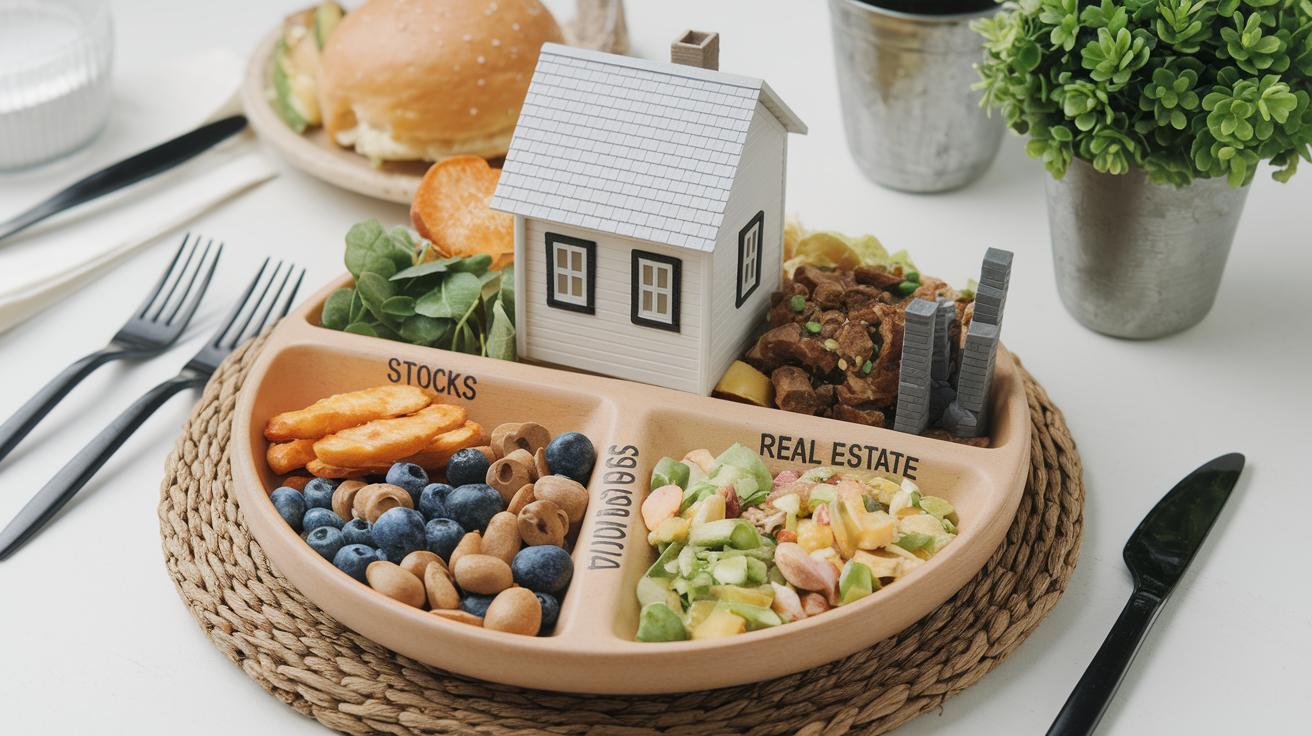
Saving and investing is a lot like making a balanced meal. You want some money close at hand for unexpected needs, and the rest working to grow over time. Stocks can help your money jump ahead (they’re shares in a company that might increase in value), while bonds provide a steadier, calmer growth (they’re like loans that earn predictable interest). Keeping a bit of cash nearby means you're ready if surprises pop up, and real estate stands strong as an asset. Many people prefer plans like a 401(k) or IRA because employers often chip in extra funds, kind of like getting a bonus when you save. And low-cost index or target-date funds give you an easy way to mix many investments without feeling overwhelmed. A simple calculator can even show you how different mixes might work, helping you decide where to put your money for both today and tomorrow.
Evaluating Investment Risk
Investing always comes with a little bit of risk. Think of it like riding your bike on a bumpy road. Some bumps, like market risk, which is when the overall market goes up and down, are normal. But other bumps, like credit or liquidity risks (that means the chance you can’t easily sell an investment), require extra care. It’s about figuring out how much of a wobble you can handle. If you get uneasy when things drop suddenly, you might lean towards more bonds instead of stocks, so your financial ride feels a bit smoother.
Portfolio Rebalancing Practices
It’s smart to check in on your investments once or twice a year to make sure they still fit your plan. Rebalancing is like tweaking the ingredients in your favorite sandwich, you might sell a little of what’s grown too big and buy more of what you need. This way, your mix stays balanced and ready to face the ups and downs of the market, keeping your overall plan on track.
Planning for Retirement within Your Personal Financial Plan
It’s smart to start thinking about retirement as soon as you can. Many folks kick off their savings with employer plans like 401(k)s or IRAs, which let you add more money and even grab a matching contribution from your boss. Imagine setting aside a bit of each paycheck and watching your savings grow over time.
A good rule of thumb is to aim for a retirement income that’s about 70–80% of your earnings before you retire. That way, your income in retirement can feel almost like your regular paycheck, which goes a long way in making you feel secure.
There are a few different strategies you might consider. Annuities, for example, can offer a regular flow of income, kind of like getting a paycheck every month. You can also plan to take out money in steady chunks (that’s what we call systematic withdrawals) to help stretch out your funds. And then there’s Social Security; planning the best time to claim your benefits can really boost your cash flow later on.
Starting early really pays off. By mixing these ideas into your overall plan, you create a solid financial framework that keeps you comfortable and secure in your retirement years.
Protecting Your Assets and Reviewing Your Personal Financial Plan
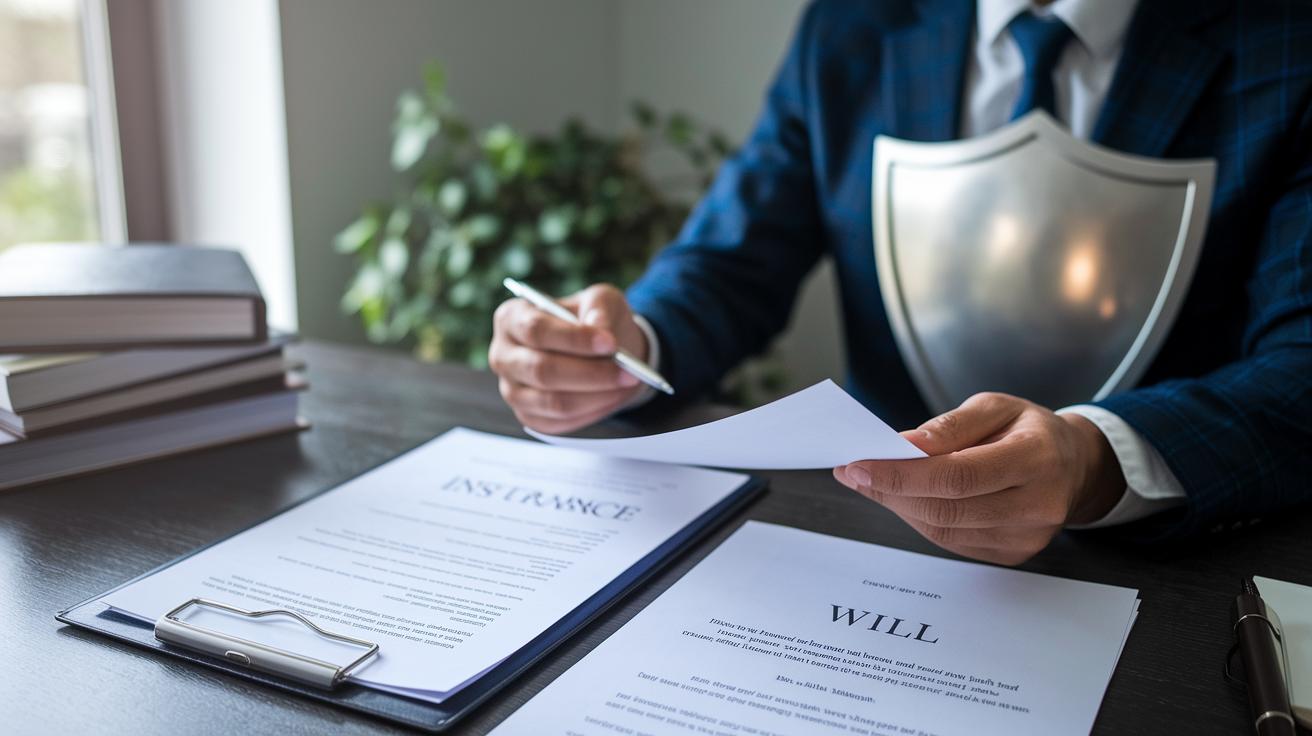
Have you ever thought about guarding your money against life’s surprises? A simple way to start is by having insurance like term life, disability, health, and property coverage. Think of these policies as a solid shield that can help you when unexpected things happen. It feels pretty good to know that a sudden health scare won’t wipe out your savings because you planned ahead.
Next, it’s smart to set up estate planning tools such as wills and trusts. These documents let you decide who gets your belongings later in life. It’s like writing a letter with clear wishes to ensure your legacy is protected.
It’s also important to check your financial plan regularly. Whether you do it once a year or after a major life change, reviewing your goals, how much you’re saving, and your overall growth is key. Picture it like a tune-up for your car, keeping everything running smoothly and catching any issues early.
Here are some easy steps to help you out:
| Step | Description |
|---|---|
| Review Your Policies | Make sure your insurance covers your current needs |
| Update Estate Documents | Refresh your wills or trusts as your life changes |
| Schedule Regular Check-Ins | Plan periodic reviews to keep your financial plan on track |
Taking these steps can make your financial plan more resilient and adaptable, keeping your future bright and secure.
Final Words
In the action, this piece breaks down personal financial planning into clear, actionable steps. It touches on tracking expenses and cash flow, setting goals for savings and retirement, and creating a smart budgeting routine. It also offers practical tips on managing debt and reviewing investments while keeping your assets safe with the right insurance and estate tools.
Each section builds on one another, helping you see how everyday choices add up to secure financial growth. Dive into your personal financial planning with confidence and watch your efforts bloom.
FAQ
Frequently Asked Questions
Q: What is personal financial planning?
A: Personal financial planning is the process of organizing your cash flow, savings, debt, and investments to meet your financial goals and secure your future.
Q: How does the 50 30 20 rule work in a financial plan?
A: The 50 30 20 rule means dividing your income so that about 50% goes to necessities, 30% to desires, and 20% to savings or debt payments.
Q: What are the steps in the personal financial planning process?
A: The personal financial planning process involves evaluating your finances, setting clear goals, crafting a budget, managing debt, and planning for savings and retirement.
Q: What does the 3 6 9 rule mean in finance?
A: The 3 6 9 rule in finance often refers to reviewing or adjusting your spending and saving plan at three, six, and nine-month intervals to keep your strategy on track.
Q: Where can I find resources like financial planning books, PDFs, or Excel templates?
A: You can find resource materials like books, PDFs, and Excel templates that guide you through budgeting, asset review, and planning to simplify personal money management.
Q: What career opportunities exist in personal financial planning?
A: Careers in personal financial planning include roles like financial advisor, planner, or analyst. These positions often require specialized degrees and certifications, with salaries reflecting their responsibilities.
Q: How is a financial plan document structured?
A: A financial plan document outlines your income, expenses, savings, debt, assets, and goals, offering a clear blueprint to manage your money and track progress effectively.
Q: How do I create a financial plan for a business?
A: Creating a business financial plan entails reviewing cash flow, budgeting, managing debts, and setting growth targets to support stability and expansion.
Q: How does financial plan AI improve money management?
A: Financial plan AI uses smart algorithms to analyze data, create personalized budgeting strategies, and offer insights that help you make more informed money management decisions.
More from Politics
 Trends
Insurance Financial Trends: Bold Market Optimism
 Digital
Open Banking And Digital Banking Convergence: Bright Promise
 Risk
Correlation Breakdown And Portfolio Risk: Robust Outlook
 Tech